PROTECTING YOUR FINANCIAL FUTURE:
WHY TIMING MATTERS WHEN FACING HARDSHIP
Life does not always follow a clean script. Job transitions, medical events, rising living costs, or unexpected personal changes can stretch any household budget past its comfort zone. When monthly expenses begin to outpace income, feeling stressed about your mortgage is completely natural.
In challenging times, the instinct is often to wait, hold on, and hope the pressure lifts next month. However, when it comes to your home, waiting often reduces your options. Taking control before you fall behind on payments is one of the most effective ways to protect your credit, preserve your hard-earned wealth, and start fresh.
Understanding the Equity Advantage
Home values across Northeast Florida have experienced sustained growth over recent years. Because of that appreciation, most homeowners today hold substantial equity—the difference between what your home is worth on the open market and what you owe on your loan.
Your home equity is real capital. As long as your mortgage remains current, that equity belongs entirely to you at the closing table. If payments are missed, late fees, default interest, and legal penalties quickly accumulate, eroding that balance month after month. Selling proactively allows you to extract that equity on your terms, turning your property into liquid savings to pay off debts, secure rental housing, and stabilize your family's finances.
Proactive Sale vs. Distressed Scenarios
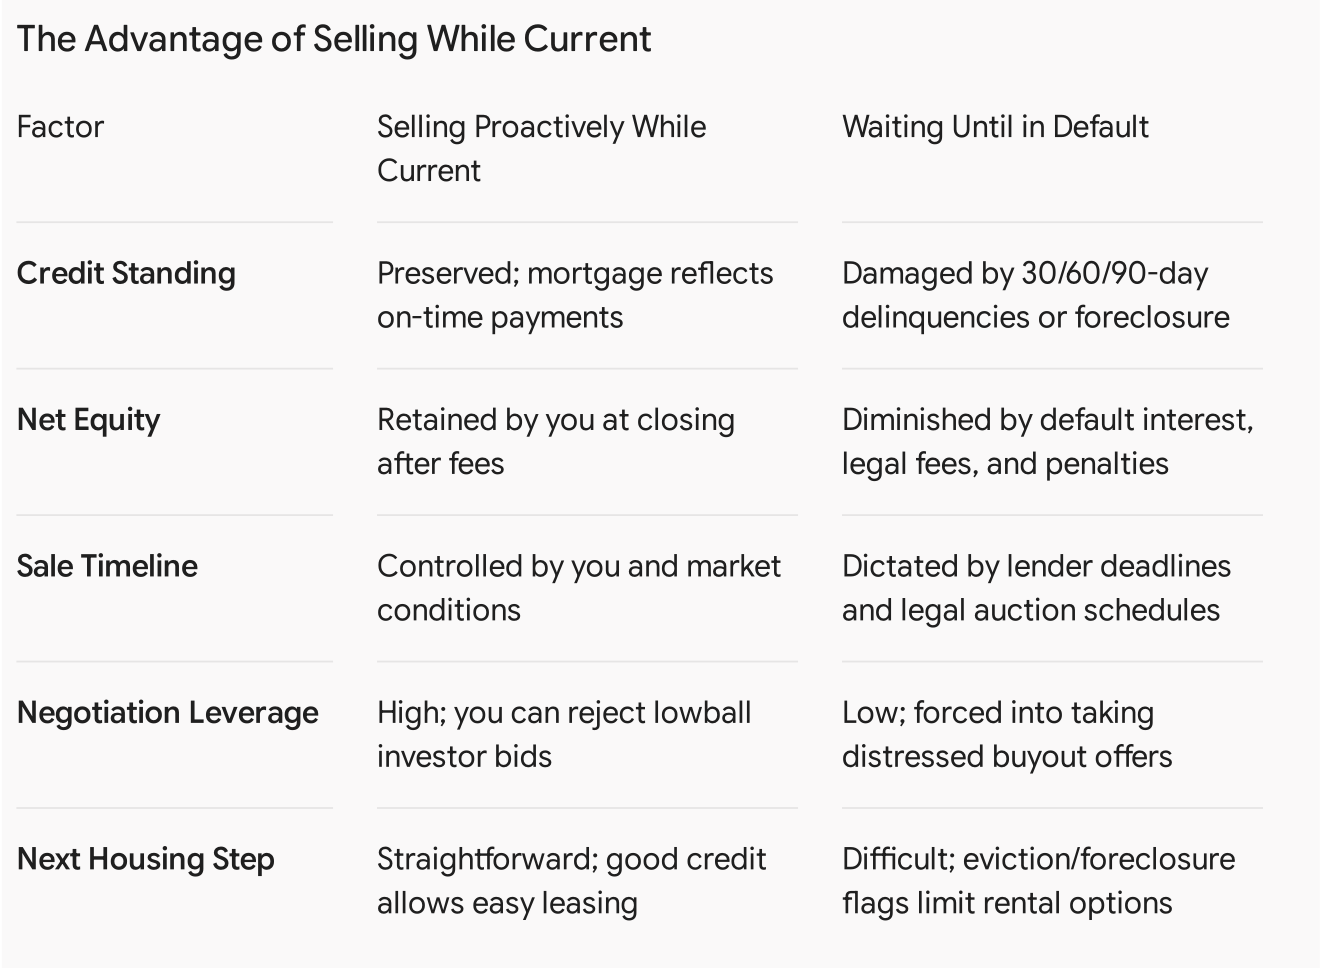
Choosing to list early creates a clean, controlled transition. Delaying until payments default forces you into distressed territory:
- A Standard Sale Keeps You in Control: You choose your listing timeline, select your representation, evaluate competitive offers, and walk away with your remaining net proceeds on closing day.
- Avoiding the Costly Toll of Foreclosure: A foreclosure damages credit scores significantly, often dropping ratings by 100 to 150 points or more and remaining on your credit profile for up to seven years. It severely restricts your ability to rent an apartment, purchase a vehicle, or secure a loan down the road.
- Steering Clear of Short Sales: If missed payments consume your remaining equity, you risk entering short sale territory—where the lender must approve selling the home for less than the owed balance. Short sales involve lengthy lender reviews, uncertain timelines, and lasting credit repercussions.
Practical Steps to Take Right Now
- Calculate your true baseline: Request an accurate payoff statement from your lender, accounting for principal, interest, and any escrow balances.
- Review a localized market valuation: Review recent comparable sales in your specific neighborhood to see what a realistic sale price looks like in today's market.
- Run a net sheet: Deduct closing costs and loan payoffs from your expected sale price to identify your estimated net equity check
- Decide early: If the monthly mortgage payment is no longer sustainable, listing while the account is current ensures you control the outcome rather than the bank.
Straightforward Guidance Without Pressure
Navigating financial stress is difficult, but you do not have to figure it out alone. An honest conversation about your property's value and market options can provide clarity on where you stand.
Reach out directly to review an objective market valuation and net sheet- confidential, grounded in local data, and focused entirely on protecting your financial well-being.
Check out this article next